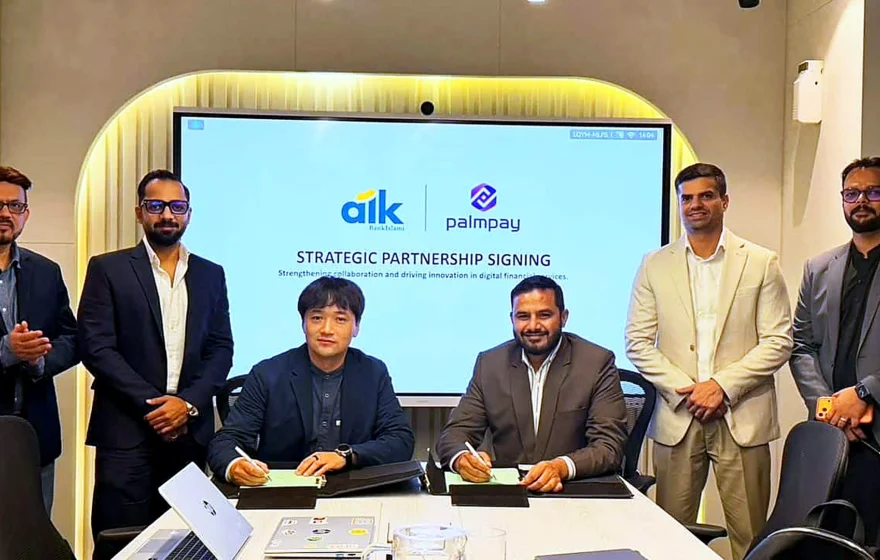
A new partnership in Pakistan’s digital banking sector is aimed at a familiar obstacle: the cost of a good smartphone. aik by BankIslami and PalmPay Pakistan have joined forces to offer Shariah-compliant smartphone financing, bringing together a fully digital Islamic banking platform and a global financial technology company in an effort to make devices more accessible without compromising religious principles.
For many people, a smartphone is no longer a luxury. It is the device through which they work, study, communicate, pay bills and access banking services. Yet a capable phone can still require a substantial one-off payment, and that upfront cost can put newer devices out of reach for students, gig workers, small business owners and families managing tight budgets. Financing, when it is designed responsibly, can spread that cost over time and allow people to obtain a device they need now, rather than waiting until they can save the full amount.
The challenge for customers who prefer Islamic banking is that conventional instalment plans are often built around interest, which is not acceptable under Shariah principles. A Shariah-compliant alternative therefore needs to be structured differently, with the financing arrangement itself aligned to Islamic finance principles. That distinction is central to this partnership. By working through aik, the partners say customers will be able to finance a smartphone in a way that fits their faith as well as their budget, rather than having to choose between the two.
aik is described as Pakistan’s first fully digital Islamic banking platform, operated by BankIslami. Being digital-first matters for this kind of product, because the customer journey, from application to approval and repayment, can be handled through an app rather than through a branch visit. That approach can reduce friction, shorten waiting times and reach customers in places where a physical branch may not be nearby.
PalmPay, meanwhile, brings experience from the wider world of digital payments and financial technology. The company operates in a number of markets and has built its name on making everyday financial services simpler and more accessible through mobile technology. In this partnership, that experience is paired with aik’s Islamic banking expertise, with the aim of creating a financing offer that is both easy to use and faithful to Shariah principles.
The leaders behind the partnership have framed it in terms of access and inclusion. Ashfaque Ahmad, Chief Officer at aik, has presented the platform’s goal as making Islamic banking accessible, everyday and effortless, and the smartphone financing offer as a practical extension of that idea. Jun Zeng, Chief Executive Officer of PalmPay Pakistan, has described the collaboration as a way to combine PalmPay’s digital payments and fintech capabilities with aik’s Islamic banking strength, so that more people can obtain smartphones through a compliant route. Together, those messages point to a shared ambition: to remove barriers that prevent people from participating fully in the digital economy.
That ambition matters because a smartphone is often the gateway to other services. Without a reliable device, it is harder to use mobile banking, receive digital payments, run a small online business, attend online classes or access government and health services that are increasingly delivered digitally. In that sense, smartphone financing is not only about owning a handset. It is about connectivity, opportunity and participation, and the groups most likely to benefit are often those who are currently underserved by traditional banking.
For the partners, the arrangement also represents a meeting point between two trends that are shaping finance in Pakistan. One is the growth of digital banking, which is lowering the cost of serving customers and allowing new kinds of products to be built around mobile technology. The other is the continued demand for Islamic finance, which remains important for a large share of the population. A product that sits at the intersection of those trends, digital and Shariah-compliant, can help both partners reach customers who might otherwise be left out.
There are, of course, questions that any financing product must answer in practice. Customers will want to understand the total cost, the length of the plan, what happens if a payment is missed, and how their data and repayments are handled. Clear terms, honest communication and responsible checks on affordability are essential if financing is to help rather than burden households. A digital process can make those checks and disclosures easier to deliver, but it cannot replace the need for them. The success of the partnership will therefore depend not only on the technology, but on how fairly and transparently the product works for ordinary customers.
If the offer works as intended, its significance will go beyond a single purchase. It could help more people stay connected, work and learn through their phones, and use digital financial services with confidence that their financing choice aligns with their beliefs. That is the promise at the heart of the aik and PalmPay partnership: to make the digital world a little more open, and to do so in a way that respects the principles of the customers it serves.
