Oil prices tumbled sharply on Monday as fresh reports of a possible breakthrough between the United States and Iran raised hopes that the eight-month-old war in the Gulf could finally be heading towards an end. Brent crude, the global benchmark, fell by around 7 per cent during the day, settling down 5.85 per cent at 92.57 dollars a barrel. The sell-off came even though Saudi Arabia’s key East-West oil pipeline was attacked on the same day, a reminder that the dangers facing energy supplies have not gone away.
The trigger was a report that quiet diplomacy between Washington and Tehran had made real progress. According to Al Arabiya, a mediation proposal put forward by Qatar and Pakistan had revived serious talks on Iran’s nuclear programme. Traders reacted at once, stripping out the war premium that has kept crude prices high for most of this year.
Pakistan-Qatar Mediation Revives the Talks
Under the proposal described in the reports, Washington would allow Iran to enrich uranium up to 3.67 per cent, the same limit set under the 2015 nuclear deal, and Tehran has agreed to accept that cap. The return of inspectors from the International Atomic Energy Agency is also being discussed, restoring outside monitoring of Iran’s nuclear sites. The figure matters because it is far below the 60 per cent enrichment level Iran had reached before the fighting began, close to the purity needed for a weapon. Accepting the old limit would be a substantial concession by Tehran.
There is, however, good reason for caution. Neither Washington nor Tehran has officially confirmed any deal, and a senior Qatari official has reportedly disputed some of the details in the media. On Sunday, US Secretary of State Marco Rubio called Tehran’s demands not just unacceptable but in some cases outrageous and ridiculous, although he added that Washington remains open to diplomacy. Qatari Prime Minister Sheikh Mohammed bin Abdulrahman Al Thani was due to meet President Donald Trump on Monday to discuss a possible ceasefire, and the American president said fresh strikes on Iran were highly unlikely while talks were making progress. That calmed the market, but it is not the same as a signed agreement.
Second Sharp Fall in Less Than a Week
Monday’s drop was the second heavy fall for oil in less than a week. Last Wednesday, Brent plunged by nearly 9 per cent to below 95 dollars a barrel after the Democratic Party swept both houses of Congress in the American midterm elections, and traders bet that the result would push President Trump towards a deal with Iran. The price fell by 8.98 dollars in a single session to settle at 94.62 dollars, its lowest close since the end of August. Over the week as a whole, Brent lost roughly 15 per cent, its steepest weekly fall since the start of the Covid-19 pandemic, after having traded near 113 dollars only days earlier. Friday brought a partial recovery, with Brent settling at 98.32 dollars as fresh attacks on tankers in the Strait of Hormuz reminded traders that the war is still very much alive.
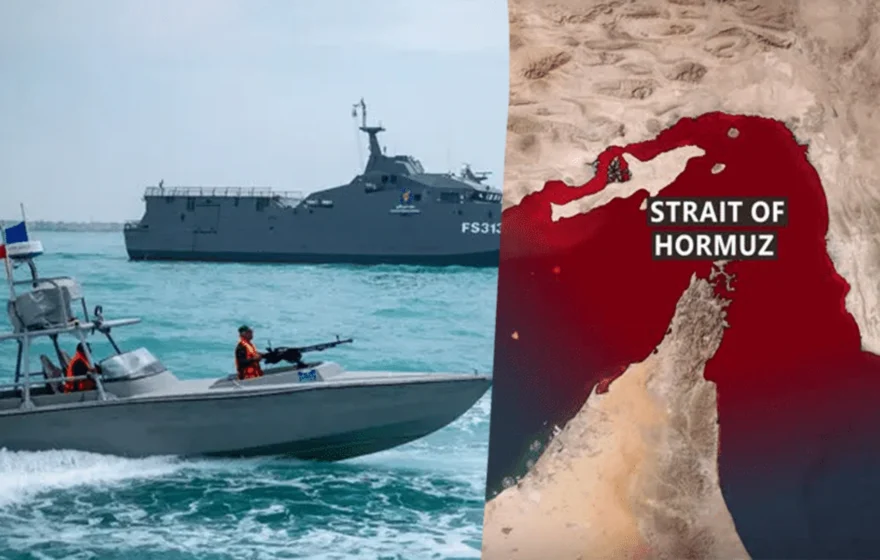
The attack on Saudi Arabia’s East-West pipeline showed why that volatility is unlikely to disappear soon. The kingdom’s energy ministry said the pipeline was targeted in the Medina region, causing a limited fire with no casualties and no disruption to supplies. The 1,200-kilometre pipeline, also known as the Petroline, carries crude from Saudi Arabia’s eastern oil fields to the Red Sea port of Yanbu, letting the kingdom ship crude without sending tankers through the Strait of Hormuz. Around 20 million barrels of oil a day normally pass through that narrow waterway, roughly a fifth of the world’s consumption, and flows have already fallen sharply since the war began. The pipeline can carry around 5 million barrels a day, making it Saudi Arabia’s most important alternative route.
For oil-importing countries such as Pakistan, cheaper crude offers genuine relief. Pakistan buys almost all of the oil it uses from abroad, so a sustained fall in prices would ease the import bill, take pressure off foreign exchange reserves and help to cool fuel prices. But the relief comes with a warning. As long as energy sites are still being attacked and no deal has actually been signed, prices could snap back just as quickly as they fell, as they did on Friday, when tanker attacks pushed Brent back up.
The coming weeks will show whether Monday’s optimism was justified. Traders will watch for any formal statement from Washington or Tehran, for the return of nuclear inspectors, and for the next meeting of OPEC and its allies on 29 November. For now, the oil market is pricing in peace before peace has arrived. If the talks succeed, millions of barrels of Gulf supply could return and prices could fall for good. If they fail, the premium will return just as fast, and importers like Pakistan will once again be counting the cost of a war fought far from their shores but felt keenly in every fuel bill.
